Insurance & InsurTech Investment Intelligence Report: Week of November 9 - 14, 2026
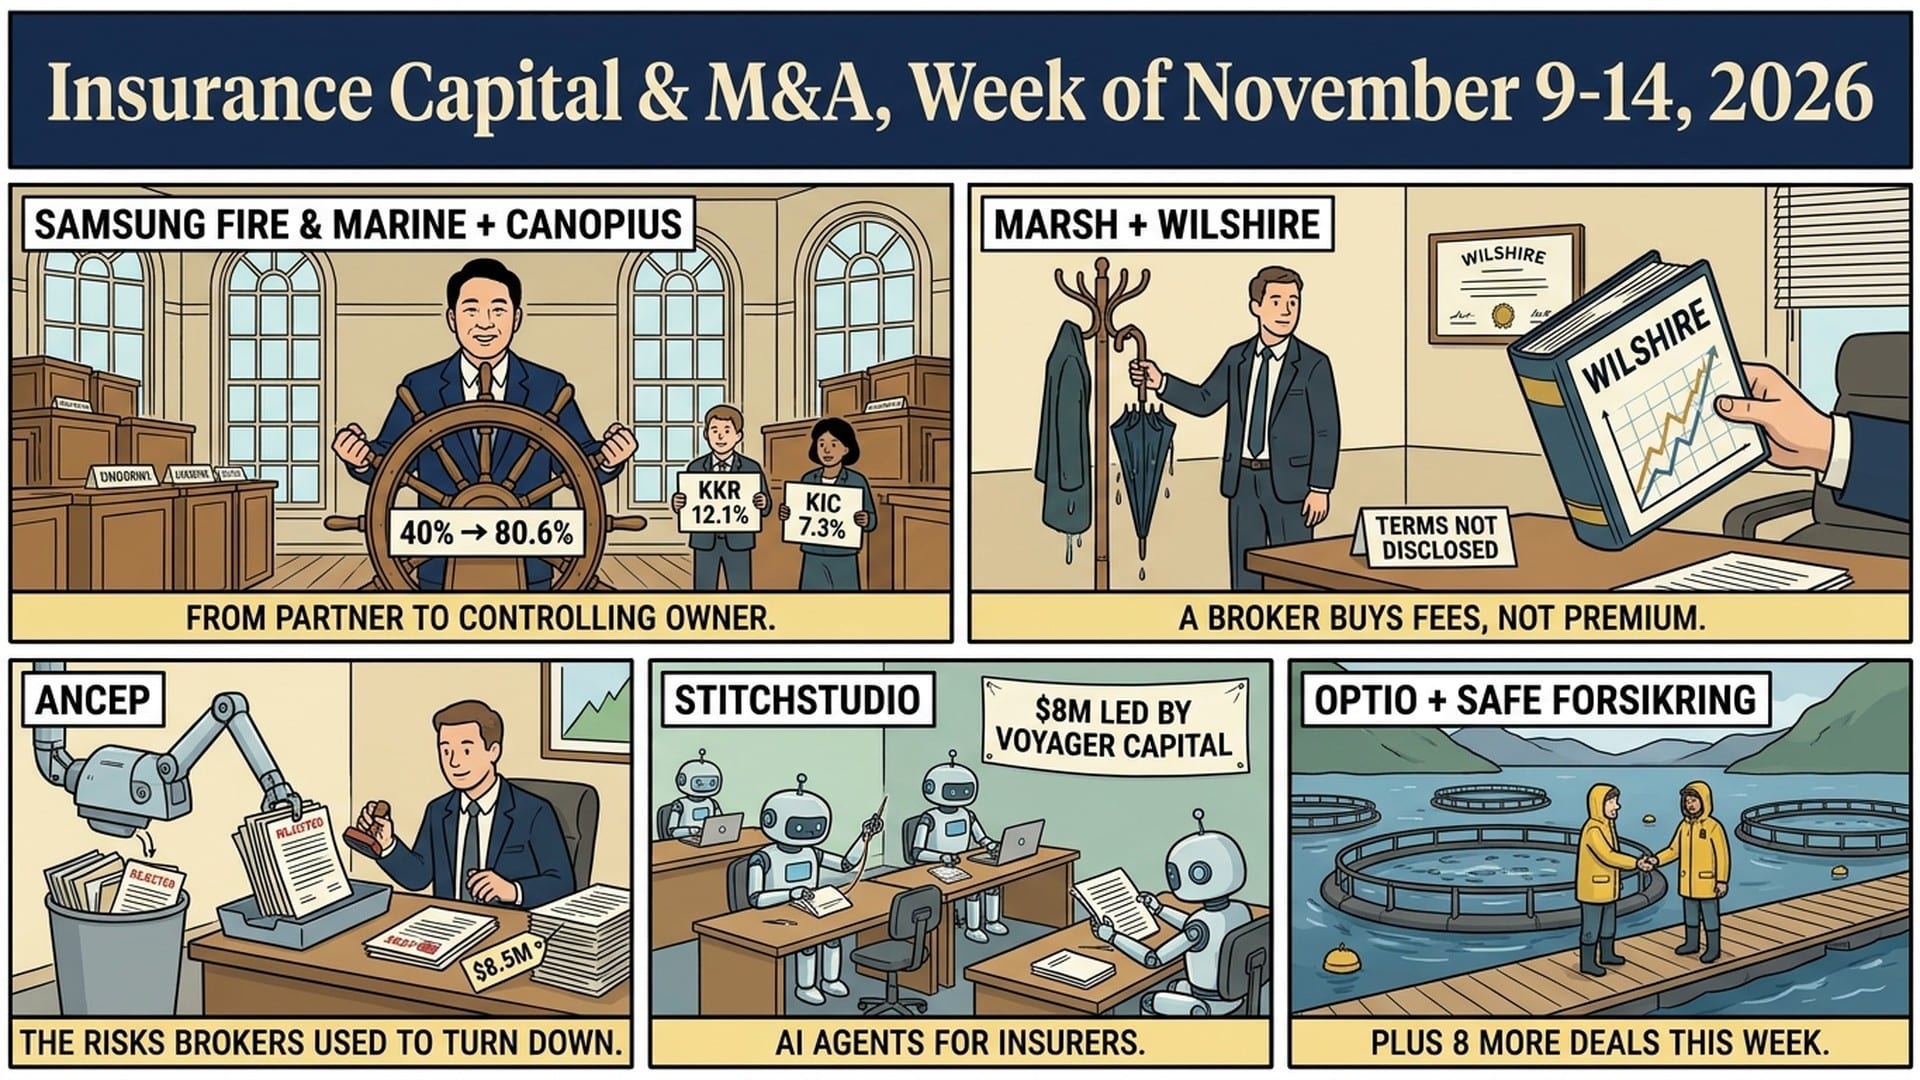
$16.5M disclosed venture funding | 13 transactions | Samsung Fire & Marine moves to control Canopius, Marsh agrees to buy Wilshire, and AI agents for brokers and insurers raise two rounds
The week’s two most significant deals were about ownership of established businesses, not new technology. Samsung Fire & Marine Insurance agreed to lift its stake in the Lloyd’s (re)insurer Canopius from 40% to 80.6%, with KKR and Korea Investment Corporation taking the rest, and Marsh agreed to buy the investment consultant Wilshire from CC Capital and Motive Partners. The venture money went to AI agents that do insurance work: Ancep raised $8.5 million for agents that help commercial brokers place risks they now turn down, and StitchStudio raised $8 million to help insurers deploy agents. Brokers, MGAs and a jewelry insurer added businesses on undisclosed terms, among them Clear Group, King Risk Partners, Ensurise, Optio Group and Jewelers Mutual Group. The $16.5 million is the sum of the two disclosed venture rounds; the Canopius price, a Form D sale and the undisclosed deals are on different bases, so the report gives no combined total.
GILAD SHAI ON THE WEEK'S DEALS: WHAT THE NUMBERS DON'T SAY
1. Canopius / Samsung Fire & Marine (UK / South Korea)
KRW 2.26 Trillion for SFMI’s Share, as Reported | Samsung Fire & Marine Agrees to Take Canopius to 80.6% Alongside KKR and KIC | Date: November 10, 2026
What Happened
Samsung Fire & Marine Insurance (SFMI) has entered into an agreement to acquire the remaining 60% stake in Canopius Group, an international specialty and P&C (re)insurer, alongside funds managed by KKR and Korea Investment Corporation (KIC), Canopius announced from London on November 10. The 60% does not all go to SFMI. SFMI will acquire an additional 40.6%, taking its total ownership to 80.6%, and KKR and KIC will hold 12.1% and 7.3%. The sellers include Fidentia Fortuna Holdings, the controlling consortium led by Centerbridge Partners.
The deal is signed, not completed: it is subject to customary closing conditions, including required regulatory approvals. Canopius’s release gives no price. Korea JoongAng Daily reports, citing a Korean regulatory filing, that SFMI will pay KRW 2.26 trillion for its share and expects to complete the purchase on March 31, 2027 once regulators approve. The filing itself was not available for this report, so the price and the completion date are the newspaper’s account, not the parties’.
- Buyer: Samsung Fire & Marine Insurance, to 80.6%
- Co-investors: funds managed by KKR (12.1%) and Korea Investment Corporation (7.3%)
- Sellers: shareholders including Fidentia Fortuna Holdings, the consortium led by Centerbridge Partners
Use of Funds
- Purchase of the outstanding 60% from existing shareholders; the release describes no new capital for Canopius.
Strategic Thesis
SFMI already held 40% of Canopius, so this is a move from large minority holder to control of a Lloyd’s specialty (re)insurer. Bringing in KKR and KIC for 19.4% between them means SFMI takes control without buying the whole 60% itself, and keeps two financial partners on the register.
For the Centerbridge-led consortium, it is an exit to the shareholder that knows the business best. For SFMI, it is a controlled position in the London specialty market, outside its home market.
Why It Matters
- A Korean carrier is taking control of a Lloyd’s (re)insurer, with an 80.6% stake once the deal completes.
- KKR and Korea Investment Corporation come in as minority holders beside a strategic owner that keeps control.
- The price is not in Canopius’s own release; the only figure available is the reported KRW 2.26 trillion for SFMI’s share.
Competition
- Direct competitors: Beazley and Hiscox, which write specialty insurance through Lloyd’s and London market platforms.
- Category competitors: MS Amlin and Tokio Marine Kiln, Lloyd’s platforms already owned by Japanese insurers.
- Emerging dynamic: Asian carriers buying control of Lloyd’s platforms to grow specialty business outside their home markets.
Market Consequences
On completion, Canopius’s brokers and capacity partners will deal with a single controlling owner rather than a private equity consortium with a strategic minority. The next disclosures to watch are the regulatory approvals the release names and, from the Korean side, the filing behind the reported price. KKR’s and KIC’s 19.4% leaves room for a later step to full ownership; nothing disclosed this week says one is planned.
Bottom line: Samsung Fire & Marine is turning its 40% of Canopius into control of a Lloyd’s (re)insurer, with KKR and KIC holding the rest.
2. Wilshire / Marsh (USA)
Terms Not Disclosed | Marsh Agrees to Acquire Investment Consultant Wilshire from CC Capital and Motive Partners | Date: November 10, 2026
What Happened
Marsh announced on November 10 that it has agreed to acquire Wilshire from CC Capital and Motive Partners. Wilshire is not an insurance business. Marsh describes it as a global investment consulting, solutions and analytics firm that serves institutional investors and financial intermediaries, founded in 1972 as an index and risk analytics provider. According to the release, Wilshire advises on over $1.6 trillion in assets and manages $221 billion, both as of June 30, 2026.
The insurance link is the buyer. Marsh describes itself as a global leader in risk, reinsurance and capital, people and investments, and management consulting, and says the acquisition expands its investments business into the advisor-led wealth segment. Financial terms were not disclosed. The deal is expected to close in the first quarter of 2027, subject to customary closing conditions, regulatory approvals and client consents. Wilshire’s colleagues in the United States, Europe and Asia will join Marsh on completion. John Doyle is President and CEO of Marsh; Jason Schwarz is CEO of Wilshire.
- Buyer: Marsh
- Target: Wilshire
- Sellers: CC Capital, a private investment firm, and Motive Partners, a private investment firm focused exclusively on financial technology and technology-enabled business services
Use of Funds
- Purchase of Wilshire from its private investment owners; the price was not disclosed.
Strategic Thesis
Marsh is buying fee income that does not depend on insurance pricing. Investment consulting and asset management earn on assets advised and managed, and Wilshire brings $1.6 trillion advised and $221 billion managed into Marsh’s investments business. The stated target is the advisor-led wealth segment, which Marsh says this deal opens to its investments business.
For CC Capital and Motive Partners, the sale is an exit to a strategic buyer. Motive Partners invests only in financial technology and technology-enabled services, and Wilshire’s analytics heritage fits that profile.
Why It Matters
- An insurance broker is buying a business that sells no insurance, to diversify where its earnings come from.
- Client consents are a closing condition, so Wilshire’s institutional and intermediary clients have a say in whether the deal completes on schedule.
- No price was disclosed for a business managing $221 billion, so the deal cannot be valued from the release.
Competition
- Direct competitors: Aon and WTW, which run investment consulting businesses for institutional investors alongside their broking.
- Category competitors: MSCI, which sells index and risk analytics to institutional investors, the business Wilshire was founded in.
- Emerging dynamic: Insurance brokers adding investment advice and wealth businesses to earn on assets as well as on premium.
Market Consequences
Aon and WTW now face a larger investment advisory competitor inside Marsh. Wilshire’s clients will want to know how its advice and analytics are kept separate from the rest of Marsh’s business. The closing in the first quarter of 2027 depends on regulators and on those clients’ consents.
Bottom line: Marsh is buying Wilshire to earn on $221 billion of managed assets, a bet that a broker’s next growth comes from investments, not premium.
3. Ancep (UK)
$8.5M Round, Round Type Not Disclosed | Creandum Leads Ancep’s Round for Broker AI Agents | Date: November 10, 2026
What Happened
London-based Ancep, which builds AI agents for commercial insurance brokers, announced on November 10 that it has raised $8.5 million. Creandum led the round, with Kleiner Perkins and Vicus Ventures participating alongside angel investors, including a former chief financial officer of Aon, according to the company. The round type was not disclosed. Founders Gagan Khurana (CEO) and Jake Turner (CTO) met at Oxford.
Ancep says its agents help brokers place the risks they currently turn down, and estimates that up to 30% of the risks a broker sees fall below that line. Only an authorised broker can bind cover, and the broking team reviews every agent output before it takes effect. The agents are live with A.C.I.C. Financial Advisory, which Ancep describes as one of the largest credit insurance brokers in Austria, and Ancep says one customer division reported a 10% revenue increase within six weeks of going live. Those are the company’s figures.
- Lead: Creandum
- Investors: Kleiner Perkins, Vicus Ventures and angel investors
Use of Funds
- Growth and hiring.
Strategic Thesis
Ancep’s pitch is about the risks a broker declines, not the ones it already places. If up to 30% of the commercial risks a broker sees are not worth placing at today’s cost, an agent that does the routine placement work turns declined business into commission. Keeping binding authority and review with the broker answers the obvious objection from compliance teams before it is raised.
Why It Matters
- The product sells to brokers, not carriers, so the buyer is the distribution side of commercial insurance.
- A named live customer in Austrian credit insurance broking gives the pitch a reference outside the UK.
- The 10% revenue figure is one customer division over six weeks; the next customers will show whether it repeats.
Competition
- Direct competitors: Ancep’s announcement names none.
- Category competitors: Applied Systems and Vertafore, which sell agency and broker management software to the same buyers.
- Emerging dynamic: AI agents that work under a broker’s binding authority, with human review of every output, aimed at risks too small to place by hand.
Market Consequences
Growth and hiring money will go into more broker deployments. Broker management software vendors such as Applied Systems and Vertafore sit in the same workflow and could build or buy similar agents. The evidence to watch is whether more brokers report revenue from risks they used to decline.
Bottom line: Ancep raised $8.5 million on the idea that brokers leave money on the table with the risks they turn down, and that agents can pick it up.
4. StitchStudio
$8M Financing Round, Round Type Not Disclosed | Voyager Capital Leads StitchStudio’s Round | Date: November 11, 2026
What Happened
StitchStudio, a startup helping insurance companies deploy AI agents, announced an $8 million financing round led by Voyager Capital, according to its investor ManchesterStory, which published the announcement on November 11. Lookout Ventures and Grit Capital Partners participated, with continued investment from ManchesterStory and a fund ManchesterStory’s page names as BokerTech Fund (Insurtech Insights reports the name as BrokerTech Fund). The round type was not disclosed. Insurtech Insights reports that the round takes StitchStudio’s total funding to $11 million.
- Lead: Voyager Capital
- Investors: Lookout Ventures, Grit Capital Partners, ManchesterStory and BokerTech Fund
Use of Funds
- Expand the product suite across employee benefits, life and annuity, and commercial property and casualty insurance, according to Insurtech Insights.
- Grow the customer success team and scale self-service tools.
Strategic Thesis
StitchStudio sells to insurers the means to put AI agents to work across their own operations. The planned product lines matter: employee benefits, life and annuity, and commercial property and casualty are three different businesses with different systems, and a vendor that covers all three can sell across a carrier group rather than to one department. ManchesterStory putting more money in is a signal of confidence from an investor already on the cap table.
Why It Matters
- ManchesterStory, an existing investor, followed on in the round.
- Two AI agent companies serving insurance raised disclosed rounds in the same week, Ancep for brokers and StitchStudio for insurers.
- A customer success team is in the use of funds, which points to deployments that need hands-on support.
Competition
- Direct competitors: None named in the announcement.
- Category competitors: Sixfold and Federato, which sell AI underwriting software to the same insurers.
- Emerging dynamic: Investors funding the layer that deploys AI agents inside insurers, not only the agents themselves.
Market Consequences
Expanding into employee benefits, life and annuity, and commercial property and casualty puts StitchStudio in front of more carrier buyers and more competing vendors. The disclosures to watch are named insurer customers, which this announcement does not give.
Bottom line: StitchStudio raised $8 million to make AI agents work across an insurer’s lines, and its next test is naming the insurers that use it.
Market Context
Optio Group announces the acquisition of SAFE Forsikring (November 9). Optio Group, an independent specialty MGA, announced the acquisition of SAFE Forsikring, an Oslo specialty MGA established by Thore Amundsen and Espen Stange that underwrites aquaculture, energy offshore and marine, for an undisclosed sum. SAFE joins Optio’s Norwegian platform alongside S Insurance and AGS Forsikring.
Ensurise completes its merger with CIS Group (announced November 10, effective October 30). Ensurise, LLC of Bethesda, Maryland announced the completion of its merger with CIS Group, a Rockville, Maryland independent brokerage specializing in commercial insurance and surety bonds, which becomes Ensurise’s newest division. Terms were not disclosed.
Jewelers Mutual Group announces the acquisition of IFS Inforsure (November 10). Jewelers Mutual Group, an insurance and business solutions provider to the jewelry industry, announced its acquisition of IFS Inforsure Inc., a Pasadena, California provider of protected shipping solutions for jewelry, watches and other high-value items. The release gives no price or closing date and says IFS expands Jewelers Mutual’s protected shipping capabilities.
King Risk Partners announces the acquisition of Lott & Gaylor Insurance (November 10). King Risk Partners, which calls itself the 36th largest insurance brokerage in the United States, announced the acquisition of Lott & Gaylor Insurance, a Fort Myers, Florida agency with over 40 years of experience in personal and commercial insurance, employee benefits and specialized coverage. The release gives no terms.
Integrity partners with Mindwell (November 10). Integrity, a life and health insurance distributor, announced that it has partnered with Mindwell Inc., a New York-based independent insurance agency. Financial details of the partnership were not disclosed.
Aquiline invests in Beni Solutions (November 11). Aquiline announced that it has invested in Beni Solutions, a Wayne, N.J. company founded in 2022 that designs and administers guaranteed-issue, ACA-compliant health plans for small and mid-sized employers. Aquiline says Beni works with approximately 700 agencies and 1,600 agents and serves more than 1,500 employer groups and over 30,000 lives; the release gives no amount or stake, and the investment is to fund sales and marketing nationwide.
Clear Group acquires Blackhawk Insurance Services (November 12). Clear Group, one of the UK’s independent insurance intermediaries, has acquired Blackhawk Insurance Services Limited, a Westcliff-on-Sea, Essex broker serving the construction sector, adding to Clear’s construction specialism. Financial terms were not disclosed.
Rockpool Investments takes a significant minority stake in vMobility (November 12). Rockpool Investments has made a significant minority investment in vMobility, which keeps policyholders and third-party claimants mobile after motor accidents by coordinating replacement vehicles and repairs for the UK motor insurance industry through its vFlo platform. vMobility, led by co-founders Danielle Corby, Matt Corby and Imesh Parmar, plans to expand its customer base, add services and grow in the corporate fleet market; the amount and stake were not disclosed.
Loti Holdings reports $3,350,001 sold in an equity offering (Form D signed November 12). Loti Holdings, Inc. filed a Form D showing $3,350,001 sold to 17 investors toward a $5,100,008 equity offering. A Form D reports sales to date, not a closed round, and it names no investors; Loti’s website describes licensed public adjusters who handle property insurance claims for policyholders.
Also noted, not counted among the week’s transactions: Pinion receives Oklahoma approval for Catlin Specialty (November 12). Pinion US Holdings LLC received Form A change in control approval from the Oklahoma Department of Insurance to complete its acquisition of Catlin Specialty Insurance Company, a US eligible excess and surplus lines writer.
FINRA disclosure: This report is for informational purposes only and does not constitute investment advice or a solicitation.