Insurance & InsurTech Investment Intelligence Report: Week of October 26 - 31, 2026 (Part 1)
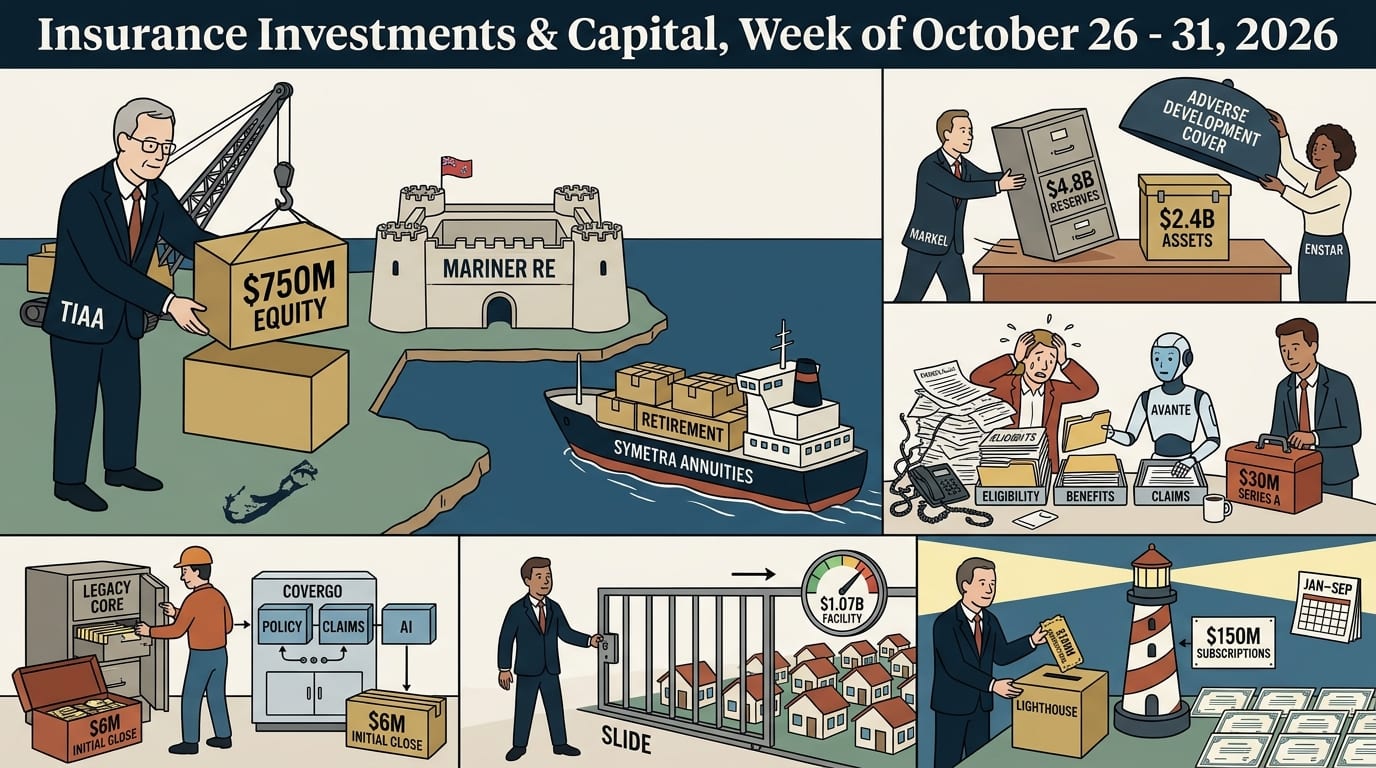
5 featured transactions | TIAA commits $750 million to a new annuity reinsurer, Enstar takes a $2.3 billion reserve layer from Markel, and venture capital backs benefits and insurance infrastructure
The biggest transactions this week were not software deals. They were about insurance capital and risk transfer. TIAA committed $750 million to Mariner Re, a new Bermuda reinsurer supporting Symetra’s annuity business. Enstar agreed to assume the last-to-pay $2.3 billion reserve layer of Markel’s discontinued reinsurance portfolio, alongside $1.2 billion of adverse development protection. One transaction puts new capital behind future annuity business. The other moves part of an existing book’s long-tail risk to a specialist reinsurer.
Technology investment was more concentrated. Avante raised $30 million to expand its AI platform for employer benefits teams. CoverGo secured an initial US$6 million Series B1 investment to develop AI capabilities and modernize insurance core systems. Aldrich Capital Partners invested in TempusDirect, a provider of medical bill review and claims cost-containment services. Ravical’s $17 million accounting-software round is adjacent technology rather than a verified insurance investment.
The other financing disclosures tell a different story. Slide Insurance Holdings expanded its credit facility to $1.072 billion, Corgi Insurance Services reported nearly $30 million sold in an equity offering, and Porch Group established an at-the-market share-sale program. These are not interchangeable measures of capital raised. This report keeps equity commitments, completed sales, credit facilities and reinsurance consideration separate. Part 2, covering acquisitions and buyouts, will follow on Monday.
GILAD SHAI ON THE WEEK'S DEALS: WHAT THE NUMBERS DON'T SAY
1. Mariner Re / TIAA (Bermuda / USA)
$750M Equity Commitment | TIAA Backs Symetra’s Annuity Growth Through a New Bermuda Reinsurer | Date: October 26, 2026
What Happened
Symetra Life Insurance Company and Teachers Insurance and Annuity Association of America (TIAA) launched Mariner Re Ltd., a Bermuda-domiciled, Class E-licensed reinsurer backed by a $750 million equity investment from TIAA.
Mariner Re will support Symetra’s annuity business through a flow reinsurance arrangement effective October 1, 2026. The October 26 announcement therefore came after the arrangement’s operating start date.
Symetra Investment Management Company and Nuveen, TIAA’s asset manager, will manage Mariner Re’s investments. Symetra Financial Corporation president and CEO Margaret Meister said the structure provides dedicated reinsurance capacity for the company’s annuity business.
- Investor: TIAA
- Reinsurer: Mariner Re Ltd.
- Operating partner: Symetra Life Insurance Company
- Investment managers: Symetra Investment Management Company and Nuveen
Use of Funds
- Equity capital to support reinsurance of Symetra’s annuity business. The announcement does not disclose how much has been funded at launch or the volume of liabilities Mariner Re will ultimately assume.
Strategic Thesis
TIAA is putting equity behind a dedicated reinsurance vehicle, while Symetra supplies the annuity business and the two groups’ investment managers oversee the assets. The structure connects retirement liabilities, reinsurance capacity and investment management within one relationship.
The $750 million is equity capital, not annuity premium or a stated reserve transfer. The amount of business Mariner Re can support will depend on the reinsurance terms, capital requirements and investment assumptions, none of which were disclosed in sufficient detail to calculate that capacity.
Why It Matters
- This is a flow reinsurance arrangement supporting new annuity business, rather than a disclosed purchase of an existing block.
- TIAA supplies the capital, while Symetra and Nuveen participate in managing the assets.
- The October 1 effective date means the arrangement was already operating before its public announcement.
Competition
- Direct competitors: Reinsurers providing capital and capacity for annuity business. No competing providers or bids were identified.
- Category competitors: Athene and other retirement platforms that combine annuity liabilities with investment-management capabilities. These are business-model comparisons, not confirmed competitors for this arrangement.
- Emerging dynamic: Annuity writers increasingly have access to dedicated reinsurance structures backed by outside equity and institutional asset-management capabilities.
Market Consequences
The next disclosure to watch is the volume of annuity business ceded to Mariner Re and the reserve base that supports it. Those figures will show how the $750 million equity commitment translates into operating capacity. They will also help establish the economics for TIAA and the capital benefit for Symetra.
Bottom line: TIAA is putting $750 million behind Symetra’s annuity growth through a dedicated Bermuda reinsurer, with investment management shared across the two groups.
2. Markel / Enstar (Bermuda / USA)
$2.4B Consideration, $1.2B Adverse Development Cover | Enstar Takes Markel’s Last-to-Pay Reserve Layer While Markel Retains the Claims Operation | Date: October 28, 2026
What Happened
Enstar Group Limited, through its subsidiary Cavello Bay Reinsurance Limited, agreed to reinsure Markel’s run-off global reinsurance portfolio and certain discontinued insurance lines for underwriting years 2025 and prior.
Enstar will receive $2.4 billion in consideration to reinsure the last-to-pay $2.3 billion of reserves within a $4.8 billion portfolio. Markel retains the first $2.6 billion. Enstar will also provide $1.2 billion of adverse development cover above the $4.8 billion of subject reserves. Markel separately identifies a $120 million risk premium.
The reserve layers are rounded figures and do not reconcile exactly to the stated portfolio total. The $2.4 billion consideration, $4.8 billion subject reserve base and $1.2 billion protection limit describe different parts of the transaction.
Markel will retain administrative and claims-handling responsibilities. Closing is expected by the end of the fourth quarter of 2026, subject to regulatory approval and customary conditions.
- Reinsurer: Enstar, through Cavello Bay Reinsurance Limited
- Cedent: Markel Insurance, the insurance operations within Markel Group
- Broker and adviser to Markel: Aon
Strategic Thesis
Markel is transferring a defined layer of long-tail reserve risk without handing over the claims operation. Enstar takes the last-to-pay layer and provides additional protection against adverse development, while Markel retains the first $2.6 billion of reserves and continues to administer claims.
This is not a complete exit from the portfolio. Markel remains exposed to the retained layer and continues to control claims handling. Enstar’s economics will depend on the eventual claims experience, the investment return on the assets supporting the liabilities and the structure of the reinsurance agreement.
Why It Matters
- Markel is transferring exposure further up the loss stack while retaining the first layer of losses.
- Claims administration remains with Markel, separating risk transfer from operational control.
- Markel expects the transaction’s net effect on fourth-quarter underwriting results to be immaterial. The agreement is primarily about managing future reserve uncertainty, not generating an immediate earnings gain.
Competition
- Direct competitors: Legacy risk-transfer specialists such as RiverStone International. No competing bidder was identified.
- Category competitors: Reinsurers providing retrospective protection and adverse development cover for existing insurance portfolios.
- Emerging dynamic: Carriers are using structured reinsurance to reduce exposure to discontinued lines while keeping their existing claims operations in place.
Market Consequences
For Markel, the question is how much reserve uncertainty remains after the transaction closes, particularly within the retained layer. For Enstar, the return will depend on claims development and the investment performance of the assets supporting the assumed liabilities.
The transaction also illustrates how legacy risk specialists can take on substantial reserve exposure without acquiring the operating infrastructure of the original insurer.
Bottom line: Enstar is taking Markel’s last-to-pay reserve layer and adding $1.2 billion of adverse development protection. Markel keeps the first-loss exposure and the claims operation.
3. Avante (USA)
$30M Series A | Frist Cressey Leads Investment in an AI Benefits Platform With More Than 70 Customers | Date: October 27, 2026
What Happened
Avante, an enterprise AI platform for employer benefits teams, raised $30 million in a Series A led by Frist Cressey Ventures. New investors Sorenson Capital, Hearst Ventures and Morgan Stanley Next Level Fund joined existing investor FUSE. Total funding now stands at $40 million.
CEO and co-founder Rohan D’Souza says Avante has more than 70 customers and supports over 385,000 employees and family members, just 18 months after launch. The company also reports that every customer eligible for renewal has renewed. Revenue and valuation were not disclosed.
Avante brings together plan documents, contracts, claims and utilization data to help benefits teams evaluate programs, negotiate with vendors and answer employee questions. Its Ava Agents beta, launched the previous week, extends the platform into recurring administrative work, with outputs reviewed by the employer team.
Carly Eckert and Kabir Shahani are also co-founders.
- Lead investor: Frist Cressey Ventures
- Investors: Sorenson Capital, Hearst Ventures, Morgan Stanley Next Level Fund and FUSE
Use of Funds
- Expand support for multinational benefits programs.
- Develop AI agents across the benefits lifecycle.
- Build infrastructure connecting employers, advisers, vendors and employees.
Strategic Thesis
Avante is selling to the employer that buys and manages benefits, rather than taking medical risk itself. Its proposition is to bring contracts, claims and employee questions into one operating system, giving benefits teams better visibility into what they purchase and how employees use it.
The customer count and renewal figures provide an early indication of adoption. The more important commercial questions are contract size, implementation costs and whether customers expand their use of the platform over time.
The participation of FUSE alongside a new lead and three additional investors also signals continued investor support for the employer-benefits technology category.
Why It Matters
- More than 70 customers and 385,000 supported employees and family members provide an early measure of platform adoption.
- The renewal claim is encouraging, although the company does not disclose how many customers have actually reached renewal.
- AI is moving beyond employee-facing benefits questions into the administrative and analytical work performed by benefits teams.
Competition
- Direct competitors: Existing benefits analytics tools, adviser-led services and employer administrative workflows. The announcement does not identify a direct software competitor.
- Category competitors: Accolade, now part of Transcarent, and other benefits navigation platforms. Their employee-support services overlap with parts of Avante’s offering, although the employer-side analytical focus is different.
- Emerging dynamic: AI platforms moving from answering benefits questions to preparing the underlying work involved in vendor management, utilization analysis and program administration.
Market Consequences
The commercial test is whether Avante can turn early adoption into larger contracts and measurable operating savings. Employers need to see improvements in purchasing decisions, administrative efficiency or employee experience to justify expanding the platform.
The reported renewal performance is an initial signal. Revenue growth, customer expansion and implementation economics will provide a better measure of the business.
Bottom line: Avante raised $30 million to automate more of the work behind employer benefits. Its customer growth is promising, but the revenue and economics behind that adoption remain undisclosed.
4. CoverGo (Singapore / Global)
US$6M Initial Series B1 Close | CoverGo Raises for AI and Core Modernization, With 25 Institutional Clients and Reported EBITDA Breakeven | Date: October 29, 2026
What Happened
CoverGo raised US$6 million in the initial close of its Series B1 round, led by Betatron Venture Group. Existing and new investors also participated, although they were not individually named. Total funding now exceeds US$30 million.
The company reports that revenue has grown tenfold since its 2022 Series A and that it has reached EBITDA breakeven. CoverGo says it serves 25 institutional clients across 15 countries. Absolute revenue, valuation and the target size of the financing were not disclosed.
CoverGo provides software for health, life and property and casualty insurers, covering distribution, policy servicing and claims. Founder and CEO Tomas Holub says the new funding will support wider adoption and the development of AI capabilities. Betatron managing partner and CEO Matthias Knobloch cited customer adoption and progress toward profitable growth.
- Lead investor: Betatron Venture Group
- Other investors: Existing and new investors, not individually identified
Use of Funds
- Develop AI-native insurance capabilities and AI agents.
- Expand go-to-market activity.
- Support insurer core-system modernization.
Strategic Thesis
CoverGo’s combination of institutional customers, reported revenue growth and EBITDA breakeven is more interesting than the AI positioning alone.
Insurance core systems are difficult businesses to build. Vendors must sell into large institutions, implement complex products and support systems that insurers depend on to administer policies and claims. Twenty-five institutional clients across 15 countries give CoverGo an established base from which to expand.
The company says revenue has increased tenfold since 2022, but without an absolute revenue figure it is difficult to assess the scale of the business. EBITDA breakeven is another positive indicator, although it does not establish positive free cash flow.
The US$6 million is an initial close, not necessarily the final size of the Series B1.
Why It Matters
- Twenty-five institutional clients across 15 countries indicate an established enterprise customer base.
- Tenfold revenue growth since 2022 provides a meaningful growth trajectory, although the starting and ending revenue figures remain undisclosed.
- Reported EBITDA breakeven suggests progress toward sustainable operations, but does not establish free cash flow profitability.
- The initial close provides additional capital without disclosing the eventual financing target.
Competition
- Direct competitors: Insurance core-platform vendors competing for policy administration, servicing and claims modernization budgets.
- Category competitors: Guidewire and Duck Creek Technologies, both established providers of core insurance systems.
- Emerging dynamic: Core-platform vendors adding AI agents to existing insurance workflows rather than positioning AI as a standalone product.
Market Consequences
The next indicators to watch are implementation time, contract expansion and customer retention. These will show whether CoverGo’s growth comes from repeatable deployments across insurers or a smaller number of large implementations.
The combination of international customers and reported breakeven gives the company a useful position as insurers consider modernization spending. The challenge is converting that position into repeatable enterprise growth.
Bottom line: CoverGo has raised an initial US$6 million Series B1 on the strength of reported enterprise adoption, tenfold revenue growth and EBITDA breakeven. The next question is how quickly it can scale those economics.
5. TempusDirect / Aldrich Capital Partners (USA)
Investment Undisclosed | Aldrich Capital Backs a Claims Cost-Containment Provider Serving P&C Insurers | Date: October 28, 2026
What Happened
TempusDirect, a technology-enabled provider of claims cost-containment and medical bill review services for property and casualty insurers, announced a strategic investment from Aldrich Capital Partners.
The investment amount and ownership stake were not disclosed.
TempusDirect helps insurers review medical charges, benchmark bills and negotiate provider settlements. Its services address the medical expenses that sit between an injury and the final payment of a P&C claim.
The announcement describes growth and continued investment in claims cost containment, but provides no transaction economics from which to calculate valuation or ownership multiples.
- Investor: Aldrich Capital Partners
- Company: TempusDirect
Use of Funds
- Support growth and innovation in claims cost-containment services. No specific allocation to product development, hiring or acquisitions was disclosed.
Strategic Thesis
TempusDirect operates in a part of the claims process where technology and specialized expertise can directly affect insurer costs.
Medical bills are not always paid at the amount initially presented. Reviewing charges, benchmarking costs and negotiating settlements can reduce the amount an insurer ultimately pays.
This is a direct insurance operating use case. Unlike underwriting software, which aims to improve risk selection before a policy is issued, TempusDirect works on the expense side of claims after an insured event has occurred.
The investment is strategically relevant, although the undisclosed amount and ownership stake prevent a meaningful assessment of the transaction’s financial terms.
Why It Matters
- Capital is going into claims cost containment rather than an insurer’s underwriting balance sheet.
- The investment reflects demand for services that can help P&C carriers manage medical expenses.
- No ownership percentage was disclosed, so it is not possible to determine whether Aldrich acquired a controlling or minority position.
Competition
- Direct competitors: Medical bill review and claims cost-containment providers serving P&C insurers.
- Category competitors: Internal insurer claims departments and outsourced claims-service providers.
- Emerging dynamic: Growth investment moving into the operational infrastructure around claims payments, an area where measurable cost savings can support a clear commercial proposition.
Market Consequences
The key metrics will be customer growth, medical bill volumes processed and the savings achieved for insurers. These would establish whether TempusDirect can translate its service offering into measurable operating value.
Without transaction terms or operating figures, the announcement provides a strategic signal rather than enough information to assess valuation or investment returns.
Bottom line: Aldrich Capital is backing a provider that works directly on medical costs inside P&C claims. The strategic fit is clear; the financial terms remain private.
Market Context: Capital & Financings
Slide expands its credit facility to $1.072 billion (October 27). Slide Insurance Holdings entered a new financing facility arranged by The Huntington National Bank, comprising a $670 million revolving credit facility and a $402 million delayed-draw term loan. The new $1.072 billion facility replaces a $530.4 million facility.
The distinction is important: these are available financing limits, not evidence that the entire amount has been borrowed. The transaction increases Slide’s financing capacity; it does not represent $1.072 billion of new equity or cash raised.
Corgi reports approximately $30 million sold in an equity offering (October 30 filing). Corgi Insurance Services reported $29,999,558 sold in a Series B-4 equity offering, with no amount remaining to be sold.
The figure comes from its Form D filing. It represents the amount reported as sold, not necessarily subscriptions completed on October 30. The filing does not establish the company’s valuation or identify investors beyond the information disclosed.
Macath reports an equity sale and a separate debt commitment (October 30 filing). Macath Solutions reported $175,000 of equity units sold and disclosed a separate $50 million committed debt facility.
These are two different financing instruments. The equity sale is a reported completed offering amount; the debt facility is a commitment, not evidence that $50 million has been drawn. They should not be combined and presented as a single funding round.
Porch establishes an at-the-market share-sale program (October 30). Porch Group and Porch Reciprocal Exchange entered into a distribution agreement with StoneX Financial permitting sales of up to 15 million common shares from time to time.
The agreement establishes a mechanism for future share sales. It does not establish that all, or any, of the authorized shares were sold during the reporting period. Proceeds and potential dilution will depend on actual sales and the applicable issuance provisions.
Scout files a fully subscribed $175,000 offering (October 27 filing; October 19 first sale). Scout InsurTech Fund, a series of Decile Start Fund LP, reported $175,000 offered and sold to five investors, with no amount remaining.
The first sale occurred on October 19, before this reporting period. The filing is included as a financing disclosure published this week, not as a round that first closed between October 26 and 31.
Hamilton extends a $330 million Funds at Lloyd’s facility (October 27). Hamilton Insurance Group announced an amendment and extension of its syndicated letter-of-credit facility through December 2030.
The $330 million facility supports Hamilton’s Lloyd’s requirements. The announcement extends existing financing capacity; it is not a new $330 million equity investment.
Lighthouse discloses $150 million of year-to-date subscriptions (October 27 disclosure). RenaissanceRe reported that Lighthouse Cat Bond Fund received $150 million in third-party subscriptions during the nine months ended September 30, 2026.
The fund operates as a segregated account of RenaissanceRe Upsilon Fund Ltd. The $150 million represents subscriptions over the first nine months of the year, disclosed during this reporting period. It is not a $150 million raise completed this week, nor does it establish net inflows or current assets under management.
Disclaimer: This report is for informational purposes only and does not constitute investment advice or a solicitation.